The Financial, Business, and Legal Benefits of Real Estate Agents Incorporating into a S-Corp or LLC
LLC or S-Corp For Real Estate Agents
The Financial, Business, and Legal Case for Incorporating
A practical operating brief for agents who want cleaner financial separation, better tax-planning conversations, stronger broker compliance, and a more credible business identity.

How real estate agents should evaluate LLC and S-Corp options
An LLC or S-Corp can help a real estate agent separate business finances, manage liability exposure, and create cleaner tax-planning conversations, but the structure works only when broker rules, payroll, bookkeeping, insurance, and professional advice are handled correctly. Confirm brokerage requirements first, model the tax impact with a CPA, review liability questions with an attorney, then align banking, records, owner pay, and marketing with the approved entity.
- An LLC is a state-law entity, while S-Corp treatment is a tax election that may be available to an eligible LLC or corporation.
- Clean separation requires dedicated accounts, consistent records, proper signatures, insurance, and disciplined handling of owner pay.
- S-Corp savings are not automatic. A CPA must compare salary, distributions, payroll costs, state rules, and income consistency.
- Broker approval controls how the entity name appears in advertising, agreements, commission instructions, and public-facing branding.
Build a Real Business Around Your License
When commission income, marketing spend, software, and professional fees all run through a personal checking account, the business becomes harder to measure and harder to defend. A formal entity can create a clearer operating boundary, but filing paperwork alone does not create protection. The entity must be formed correctly, funded correctly, insured properly, and respected in daily operations.
The decision is not simply LLC versus S-Corp. An LLC creates a legal container under state law. S-Corp treatment changes how an eligible entity is taxed and how owner pay may be structured. Your advisors must decide whether the legal entity solves a real operating problem and whether the tax election justifies added payroll and compliance work.
Agents who already think like full operators in The Full-Stack Agent: Why a Multi-Channel Marketing Plan is Your Path to Success can treat entity structure as the financial and legal layer beneath that same operating mindset.
- Separate personal and business money with dedicated entity accounts.
- Ask a CPA whether income consistency supports payroll and S-Corp tax modeling.
- Ask an attorney how state law, liability exposure, insurance, and corporate-veil discipline apply.
- Ask your broker how entity names, DBAs, advertisements, signatures, and commission payments must be handled.
Sole Proprietor, LLC, and S-Corp Decision Logic
A sole proprietor and the business are often treated as one practical bucket. The commission check, debit card, software bill, advertising spend, and tax records can blur together. An LLC or corporation creates a separate legal container under state law. An S-Corp election, when appropriate, changes the tax treatment and owner-pay process.
The best answer depends on income, broker policy, state rules, expense discipline, payroll readiness, and risk. Use the framework below to prepare for conversations with your CPA, attorney, and broker. It is not a substitute for legal or tax advice.
Simple, but often blurred
Formation is minimal, but business money and personal money can be harder to separate. Tax records and operating discipline depend almost entirely on the agent’s habits.
Legal and operating separation
An LLC may create a clearer legal container when maintained correctly. It is often simpler for a solo agent than a corporation, but brokerage approval and state compliance still matter.
Tax planning with more discipline
S-Corp treatment may create salary and distribution planning opportunities. It also requires payroll, reasonable salary support, added filings, and tighter bookkeeping.
| Decision Point | LLC Focus | S-Corp Focus | Advisor Question |
|---|---|---|---|
| Primary purpose | Creates legal and operating separation when maintained correctly. | Creates possible tax-planning options through salary and owner distributions. | What problem am I solving first: risk separation, tax planning, or both? |
| Complexity | Usually simpler to form and operate for a solo agent. | Requires payroll, reasonable salary support, tax filings, and more coordination. | Are my books clean enough to support the extra compliance? |
| Brokerage approval | May require approval for entity payments, advertising disclosures, and public name usage. | Requires the same broker coordination plus payroll and tax-election timing. | Will my broker approve how the entity appears in contracts and marketing? |
| Best timing | Often useful when the agent wants cleaner records and business separation. | Usually worth exploring when net commission income is consistent and predictable. | At what income level does the math work in my state? |
What Formal Incorporation Can Improve
The first benefit is separation. When the entity is formed, funded, insured, and respected, it can help separate business risks from personal life. That does not make lawsuits disappear, and it does not replace errors and omissions coverage, broker supervision, or strong transaction practices. It gives the business a more defensible operating structure.
The second benefit is cleaner tax planning. Once a CPA sees consistent commission income, the advisor can model whether S-Corp treatment may reduce self-employment tax after payroll costs, professional fees, state rules, and reasonable salary requirements are considered. The savings are not automatic. The math must be modeled.
The third benefit is credibility. Clients, lenders, vendors, and other agents notice whether the business looks organized. Clean entity naming supports higher-end positioning, stronger listing materials, and more serious investment in marketing systems like the approach described in How to Attract High-End Buyers and Sellers in Today’s Market.
Use net commission income as the trigger, not ego. For many agents, the S-Corp conversation begins around $60,000 to $75,000 in consistent net commission income, but the correct threshold depends on state rules, expenses, payroll costs, professional fees, and the agent’s growth plan.
Structural Mistakes That Weaken the Entity
Filing paperwork is not the same as running a separate business. The entity must be respected after formation. Common mistakes can erase much of the operating value the agent was trying to create.
- Paying personal bills from the business account or business bills from a personal card blurs the line between the agent and the entity.
- Using an entity name in advertising, signatures, or commission instructions before brokerage approval can create compliance problems.
- Ignoring state filings, registered agent mail, business licenses, and basic corporate records weakens operational credibility.
- Electing S-Corp treatment without a defensible salary and payroll process undercuts the strategy.
- Routing ad spend, email tools, website costs, direct mail, and software through inconsistent accounts makes tax review and growth planning harder.
Eight Steps to Form and Operate the Entity
The order matters because entity setup touches state filings, tax timing, broker policy, banking, payroll, and public-facing marketing. Use this roadmap to organize the right conversations.
- Meet with a CPA and business attorney who understand real estate income, state rules, and entity operations.
- Gather last year’s commission income, current pipeline, software costs, marketing spend, mileage, professional fees, and projected growth.
- Ask how your brokerage handles entity names, team brands, DBAs, advertising disclosures, commission payments, and contract signatures.
- Decide whether an LLC, corporation, or another approved structure is appropriate under state law and brokerage rules.
- Keep stamped formation documents, receipts, and state approval letters in a digital entity folder.
- Use the IRS EIN process for the entity, then use that tax identity for bank accounts, vendor records, and payroll setup.
- Route commission income and business expenses through entity accounts so bookkeeping and advisor review become easier.
- After broker and advisor approval, align your IDX Real Estate Websites, email signature, social profiles, business cards, listing presentations, and closing templates with the approved entity language.
Professional Messaging That Reinforces Credibility
Once the structure exists, every public touchpoint should quietly reinforce that the client is hiring an organized business. The goal is not to sound larger than you are. The goal is clarity, consistency, and broker-approved professionalism.
An email signature can identify the agent as founder of the approved entity. A website footer can connect the legal entity to the licensed real estate service area. Contracts, invoices, vendor accounts, and tax records should use the approved legal language consistently.
A listing presentation can show that pricing, marketing, communication, and reporting are operated through a defined company system. The brand should feel organized without making claims that exceed the agent’s actual structure or broker authority.
Support the structure with visible proof that your systems work. Reviews, testimonials, and short client stories can connect the professional identity to actual client confidence, as outlined in Beyond the Just Sold: How to Leverage Client Testimonials and Social Proof. Reinforce the same identity through steady channels like Email Marketing for Real Estate Agents, so the entity name becomes familiar before the next listing or buyer agreement.
What It Costs to Maintain the Structure
Entity setup has real cost. The better question is not what the cheapest filing option is. The better question is what it costs to create clean records, sound advice, payroll discipline, and a structure that can survive review later.
| Cost Category | Low Estimate | High Estimate | Cadence |
|---|---|---|---|
| State filing | $100 to $500 for basic online formation | $500 to $1,000 with rush handling | Paid once when the entity is formed |
| Advisor setup | $300 to $700 for targeted guidance | $1,000 to $2,500 for full formation support | Paid once when structure and filings are designed |
| Annual renewal | $50 to $300 for state reports and basic filings | $100 to $500 when an advisor handles the work | Paid each year to keep the entity active and clean |
| Payroll support | $100 per month for software and self-managed payroll | $300 to $500 per month for full-service support | Paid monthly or quarterly once salary and draws are active |
How to Know Whether the Structure Is Working
The entity should produce more than a folder of state documents. It should create clearer books, cleaner advisor conversations, and better decisions about where profit goes next. These planning metrics help an agent and CPA review whether the structure is doing useful work.
| KPI | What It Tracks | Planning Range | How to Use It |
|---|---|---|---|
| Tax savings | Estimated self-employment tax retained after added costs | $4,000 to $8,000 | Review with a CPA and confirm that savings justify payroll, software, and advisory costs. |
| Admin hours | Time spent on bookkeeping and compliance work | Four to six hours per month | Track time before and after outsourcing so more capacity can return to clients and lead generation. |
| Documented spend | Legitimate annual business expense flowing through the entity | $30,000 to $60,000 | Route campaigns, tools, and Direct Mail Marketing through clean records so the spend is easier to document and evaluate. |
This is where business structure and marketing operations connect. When Retargeting and contextual digital advertising, email tools, website work, software, and mail campaigns flow through clear entity records, the CPA can see the true cost of growth and the agent can decide whether the next dollar should go to marketing, reserves, payroll support, or owner compensation.
Legal Boundaries and Ethical Operations
The entity only has value if it works with the license and brokerage. The agent still works under a broker, and in many markets the broker must approve entity naming, written agreements, advertising language, and how commission is paid. Every structural change should be cleared before contracts are signed or marketing appears under the new name.
Maintain the corporate veil through ordinary discipline. Keep business and personal money separate. Document major decisions. Sign contracts with the entity name and title that match filings and broker approvals. The goal is to make it easy for a court, regulator, broker, lender, or auditor to see that the difference between the agent and the company is respected.
Agent Alex C and the $6,000 Tax Shift
Agent Alex C earned $120,000 in gross commission income as a sole proprietor and paid self-employment tax on that entire amount. After review with a CPA and attorney, Alex formed an LLC, elected S-Corp treatment, and set a reasonable salary of $60,000 based on role expectations and local pay data.
The remaining $60,000 moved out as owner distributions that were not subject to the same self-employment tax treatment. Once payroll tools and professional fees were included, roughly $3,000 a year went to administration and support. The net self-employment tax savings landed near $6,100 per year.
The scenario is illustrative, not a promise. The useful lesson is that the tax, payroll, and administrative math becomes visible when the business is structured and measured. Every agent needs individual advice based on income, state law, broker policy, and reasonable salary requirements.
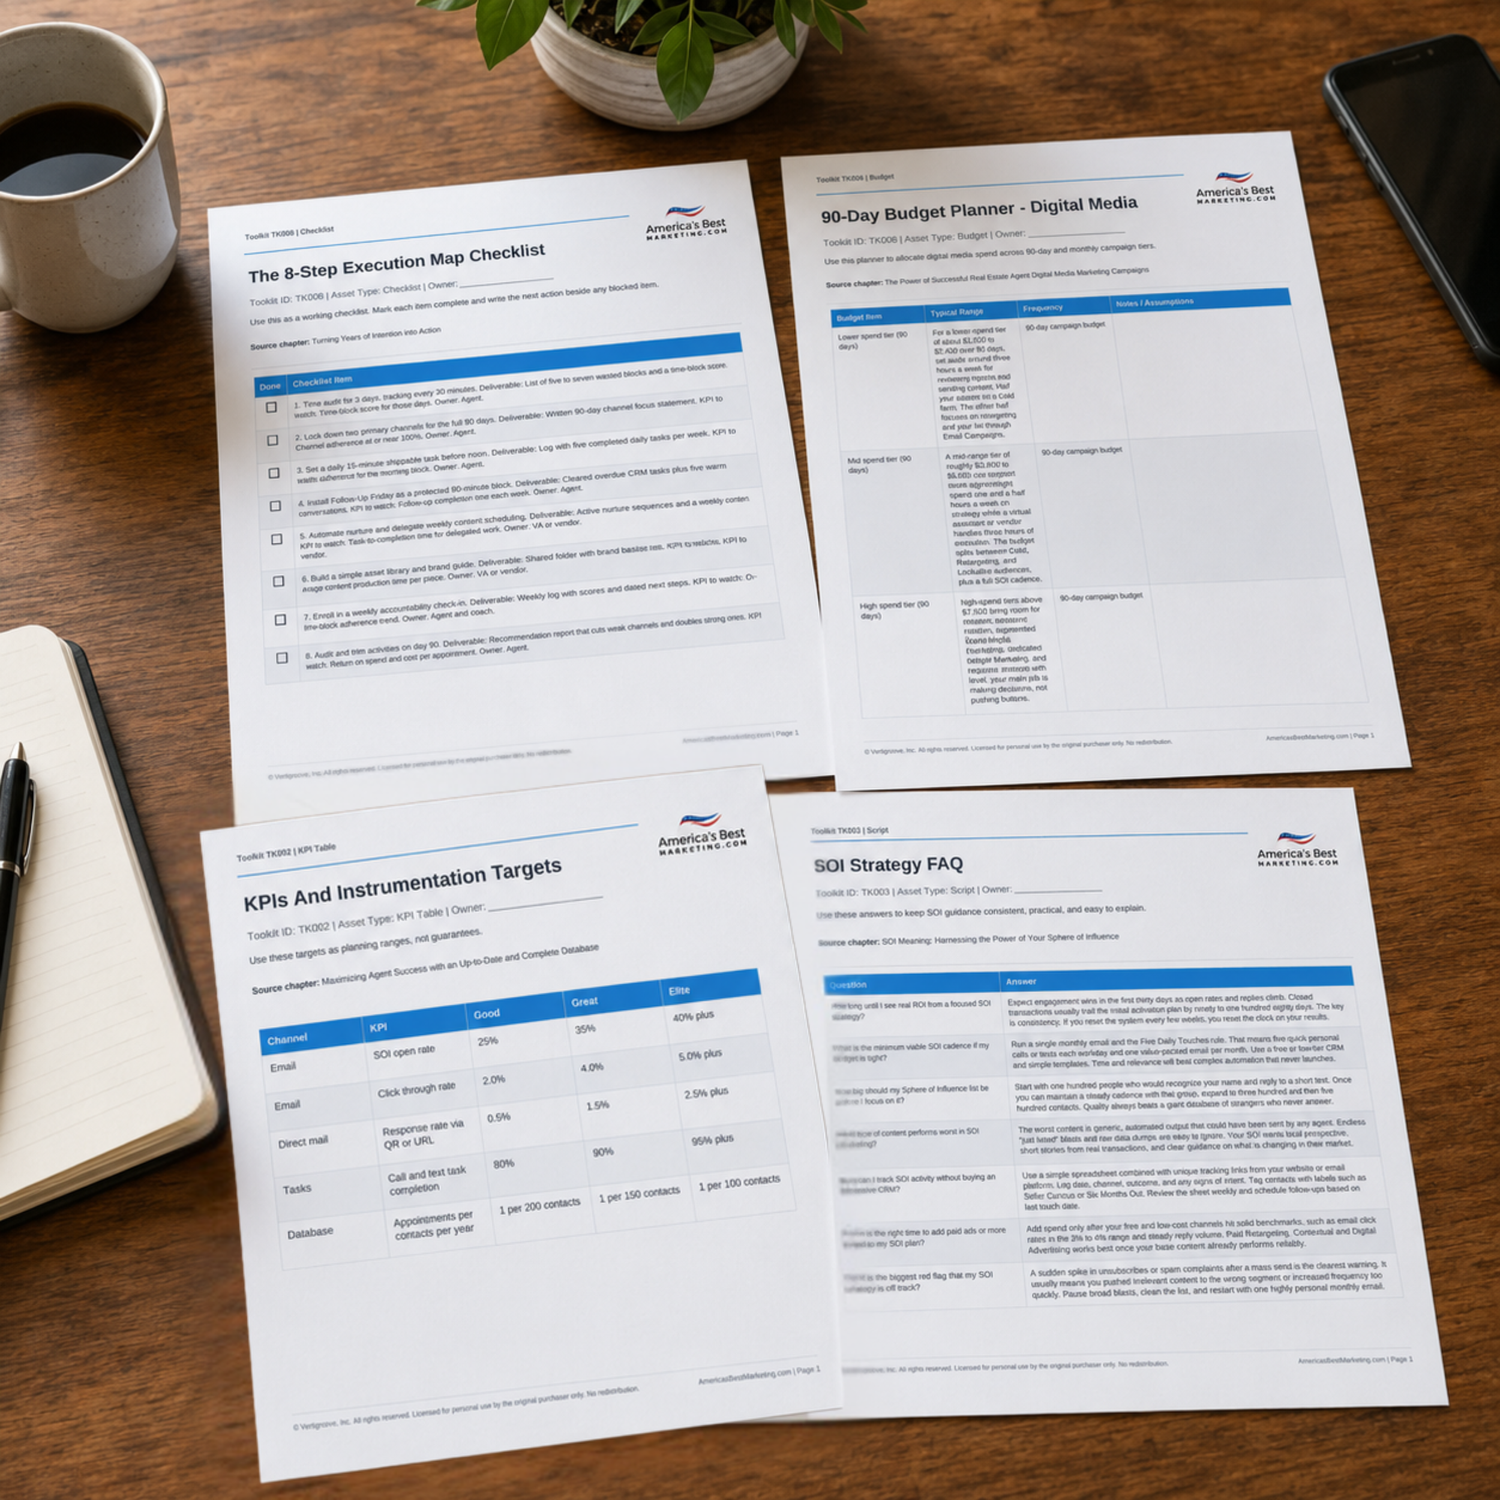
Download the Real Estate Entity Planning Toolkit
The TK105 ZIP includes an entity-formation roadmap checklist, budget range worksheet, KPI snapshot, and entity-structure FAQ script to organize the next CPA, attorney, and broker conversation.
Download the Toolkit ZIPRecommended reads
Recommended Reads for Real Estate Agents
These articles help agents connect follow-up discipline, database habits, client communication, and marketing execution into a repeatable system.

Financial Literacy for Real Estate Agents: Your Guide to Budgeting and Investing in Your Business
Make financial literacy more useful by tying the message, audience, and next step together.
Read article
HOA Navigation for Real Estate Agents: Red Flags, Document Requests, and Buyer Scripts
Give hoa navigation a clearer role in the marketing system instead of treating the work as a one-off idea.
Read article
Google Business Profile for Real Estate Agents: Ranking & Review Scripts
Make Google Business Profile more useful by tying the message, audience, and next step together.
Read article
Business Growth Strategy for Real Estate Agents
Use business growth planning to strengthen visibility, follow-up, and client conversations without adding more random tasks.
Read articleLLC and S-Corp Questions Real Estate Agents Ask
How long does it take to see measurable results from an S-Corp structure?
The legal protection starts as soon as the entity is formed and respected in daily operations. Financial results show up at tax time once a full year of income has run through the new structure. You will see the clearest picture after your first full year of returns under the advice of a CPA who understands real estate income.
What is the minimum annual income that makes an S-Corp worth exploring?
Many advisors start the conversation once net commission income lands in the $60,000 to $75,000 range each year. Below that level, payroll and advisory costs can wipe out much of the benefit. The exact line will depend on your market, fixed expenses, state rules, and how aggressively you reinvest profits into growth.
How does an LLC or S-Corp change my relationship with my broker?
Your license still hangs with the broker, and brokerage rules still control how you advertise and sign agreements. The main change is that commission checks and contracts may reference the entity instead of your personal name when the broker approves that structure. Larger firms often use a standard addendum or policy to document this, which is one more reason to involve the broker early.
What is the biggest red flag that could pierce the corporate veil?
The largest risk is commingling funds. Paying personal bills from the business account, or paying business expenses like email marketing subscriptions from a personal card, blurs the line between you and the company. Over time that pattern makes it easier to argue that the entity is just a shell.
How do I choose between starting with an LLC or going straight to an S-Corp election?
Many agents create a simple single-member LLC first for liability and operational clarity. Once income is stable at the levels your CPA recommends, you can elect S-Corp taxation for that same LLC if eligible. That path creates flexibility because you gain some separation early and delay payroll complexity until the math clearly supports it.
Can I file the entity paperwork myself without hiring professionals?
Most agents can follow state instructions to file basic formation documents on their own. The larger risk appears when you set salary levels, decide whether and when to elect S-Corp status, and start taking distributions. Those choices can create tax exposure, which is why a CPA should lead that part of the work even if you handle basic state filings.
Does my new entity name have to match my public-facing brand name?
The legal entity name and your public brand do not need to be identical, yet they must be clearly linked. The entity name belongs on contracts, checks, and tax records. Any team brand or trading name should be properly filed and tied back to the entity in state and brokerage records so there is no confusion about who stands behind the work.
Next step
Build the System Behind the Structure
Continue from one operating decision into the larger ABM ecosystem: the book series for strategic depth and the full marketing program for done-for-you execution.

View the Book Series
Explore the America’s Best Real Estate Agent Marketing System books for a deeper strategic framework around visibility, referrals, listings, lead generation, and growth.
View the Book Series
See Full Marketing Program
See how AmericasBestMarketing.com runs real estate blog writing, social media, listing marketing, email, direct mail, and retargeting as one managed system.
See Full Marketing Program